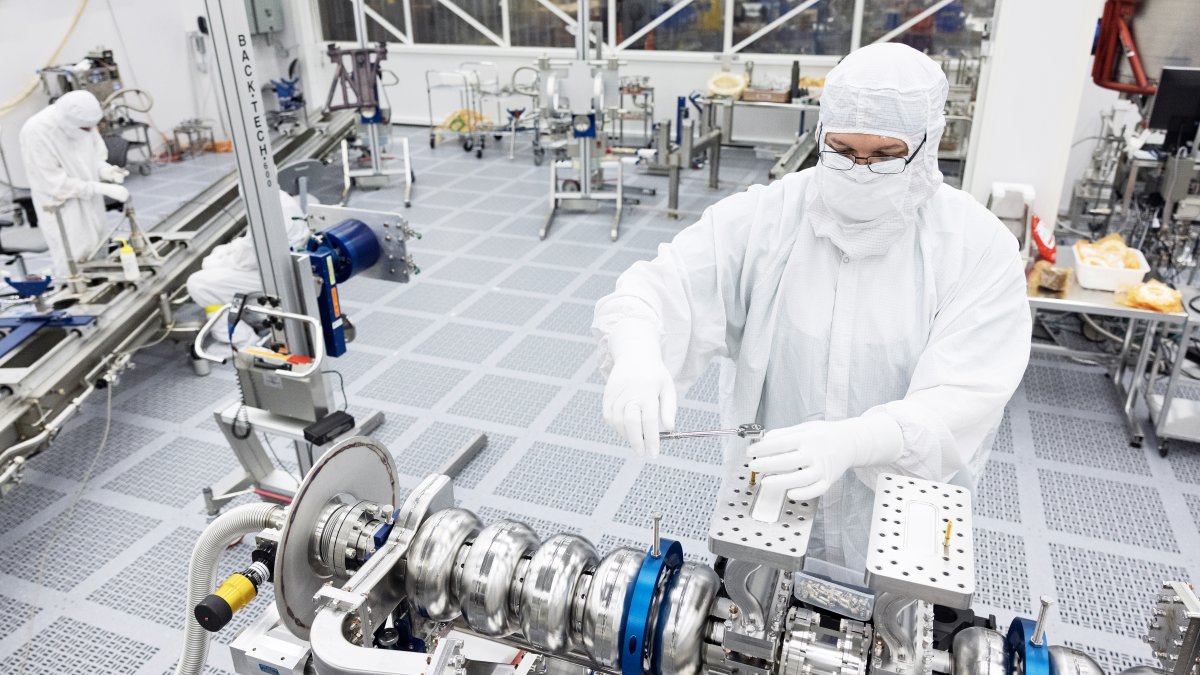
NVIDIA used its first GTC in Berlin to publish something unusual for a keynote built on chips: a procurement map. The company announced capacity agreements with six suppliers — Amkor Technology, IBIDEN, King Yuan Electronics (KYEC), Samsung Electro-Mechanics, Siliconware Precision Industries (SPIL) and Unimicron Technology — covering substrates, advanced packaging, testing and optical engines, the unglamorous layers that actually gate how many AI systems can ship. "We are in the midst of the largest infrastructure buildout in human history. Demand is extraordinary. Capacity is the constraint," founder and CEO Jensen Huang said in the announcement.
The substrate commitments anchor the package. NVIDIA plans to lift substrate capacity for its products by 2.5x over the next three years. IBIDEN is receiving a multibillion-dollar capacity reservation advance for its Ono plant in Japan, targeted to reach three times current capacity, with additional output beginning to ramp in the first quarter of 2028. Samsung Electro-Mechanics joins the substrate supply chain with immediate capacity from existing Korean operations, plus upgrades and new factories in Sejong and Busan; by 2028, production allocated to NVIDIA is projected to account for a significant portion of its total annual package substrate capacity. Unimicron is expanding KF substrate lines in Taiwan under a capacity reservation agreement, starting to add volume in the second quarter of 2027 and reaching full capacity by mid-2028.
Advanced packaging gets a parallel commitment. NVIDIA and Amkor plan to expand capacity in South Korea, targeting an increase of more than 300 percent in interposer wafer capacity by the end of 2028, alongside new Amkor manufacturing facilities in the country. Interposers are the bridge between compute dies and high-bandwidth memory, and they have been one of the tightest links in the supply chain for every recent GPU generation.
Testing capacity is the third leg. NVIDIA expects its total semiconductor testing capacity to double from calendar 2026 to 2027, supported by buildouts in the United States, Taiwan and Singapore. A 1.1 billion dollar capacity reservation advance to KYEC will fund new US testing facilities and equipment, with high-volume production targeted for April 2027; expanded operations in Singapore are expected to begin high-volume production in February 2027.
The optics piece points at where rack-scale systems are heading. NVIDIA and SPIL plan to expand manufacturing in Taiwan for the optical engines used in co-packaged optics, targeting a 15x capacity increase by mid-2027, with aims for another doubling by the end of 2028 — roughly 30x the current baseline. Co-packaged optics matters because fiber can carry far more data per watt than copper once signals leave the package, and hyperscale AI factories are rapidly running into that physics.
The announcement pairs with the DSX POD modular AI factory design unveiled in the same keynote: Vera Rubin compute racks, cabling and liquid cooling integrated and tested in a factory, then delivered as containers, cutting on-site deployment from about six months to as fast as 14 days where site power is ready, with Dell, HPE, Lenovo and Schneider Electric products planned for early 2027. The two moves are complementary — prefabrication attacks on-site labor time, while capacity reservations attack component lead-time risk.
The strategic read is that NVIDIA is converting supplier relationships into reserved, prepaid capacity the way it once converted developers into CUDA users. Capacity reservation advances bind output to NVIDIA before competitors can claim it, and Samsung Electro-Mechanics entry adds a second source in a layer long concentrated in a handful of Japanese and Taiwanese firms. The exposure is real if AI demand stalls — committed capacity and advances do not refund themselves — but in a market where the constraint is supply rather than orders, NVIDIA has decided the cheapest insurance is to buy the bottleneck outright.
Comments (0)
Log in to join the discussion
Log InNo comments yet